A Property and Financial Affairs Lasting Power of Attorney can give someone you trust legal authority to help manage your money and property.
But one of the most common misunderstandings is that making an LPA means immediately handing over control of your finances.
It does not.
You remain in control of your own decisions while you have mental capacity.
A registered Property and Financial Affairs LPA simply creates a legal framework that allows your chosen attorney or attorneys to help you — either with your permission while you still have capacity, or later if you become unable to make the relevant financial decisions yourself.
That can include anything from helping with bills and bank accounts to dealing with investments or property, depending on the authority contained in the LPA.
What is a Property and Financial Affairs LPA?
A Property and Financial Affairs Lasting Power of Attorney, often shortened to Property and Financial Affairs LPA, is a legal document used in England and Wales.
It allows you, as the donor, to appoint one or more people you trust as your attorneys.
Your attorneys can then make financial decisions for you within the authority given by the LPA.
Typical areas can include:
- managing bank and building society accounts;
- paying bills;
- dealing with pensions and benefits;
- managing savings and investments;
- dealing with tax matters;
- buying or selling property where authorised;
- managing rental property; and
- handling other financial arrangements.
The precise authority depends on the wording of the LPA and the circumstances.
When can a Property and Financial Affairs LPA be used?
A Property and Financial Affairs LPA must be registered with the Office of the Public Guardian before it can be used.
Once registered, it can potentially be used while you still have mental capacity, if you have chosen to allow this.
That makes it different from a Health and Welfare LPA, which can only be used when the donor lacks capacity to make the particular health or welfare decision themselves.
This can be useful where someone still understands and makes their own financial decisions but would like practical help.
For example, you may want an attorney to help because:
- mobility makes visiting a bank difficult;
- you are spending time abroad;
- paperwork is becoming burdensome;
- you want somebody to help with household finances;
- illness temporarily makes financial administration harder; or
- you simply want trusted support available if needed.
You do not automatically lose control because your attorney starts helping.
While you have capacity, your decisions remain your decisions.
Can my attorney take over my finances while I still have capacity?
Not simply because an LPA exists.
An attorney must act within the authority provided by the LPA and in accordance with their legal duties.
If you still have capacity to make the relevant decision, your attorney should not simply override you.
A registered Property and Financial Affairs LPA may allow the attorney to act with your permission while you still have capacity, but the arrangement is intended to support you rather than remove your independence unnecessarily.
This distinction is important.
An LPA is not the same as signing away control of your finances.
What happens if I later lose mental capacity?
If you later lose the mental capacity to make a particular financial decision, your attorney can continue to act within the scope of the registered LPA.
This is one of the main reasons people put a Property and Financial Affairs LPA in place in advance.
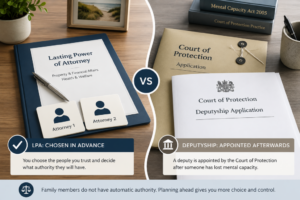
Without suitable authority already in place, family members do not automatically gain legal power to manage your finances.
Where no valid LPA or other authority exists, it may become necessary to consider an application to the Court of Protection for deputyship or another appropriate order.
Our guide Lasting Power of Attorney vs Deputyship explains that difference in more detail.
What can an attorney do under a Property and Financial Affairs LPA?
Depending on the LPA, attorneys may be able to deal with matters such as:
Bank and building society accounts
An attorney may be able to:
- pay bills;
- transfer money;
- manage direct debits;
- deal with account administration;
- open or close accounts where appropriate; and
- speak to banks or building societies on the donor’s behalf.
Banks and other financial institutions will normally need evidence of the attorney’s authority before allowing access.
Benefits and pensions
An attorney may be able to deal with:
- pension income;
- state benefits;
- applications and correspondence;
- payments; and
- financial administration connected with those benefits.
Investments and savings
Depending on the terms of the LPA, an attorney may be able to manage:
- savings accounts;
- investments;
- investment income; and
- financial products.
Attorneys must act carefully and in the donor’s best interests where the donor lacks capacity.
Property
An attorney may be able to manage property, including:
- paying household costs;
- dealing with insurance;
- arranging repairs;
- managing rental property; and
- selling property where the authority and circumstances allow.
Property transactions can involve additional legal and practical issues, so attorneys should not assume that every transaction is automatically covered simply because they hold an LPA.
Can an attorney sell my house?
Potentially, yes.
A Property and Financial Affairs LPA can allow an attorney to deal with the donor’s property, including a sale, provided the attorney has the necessary authority and is acting lawfully.
However, property sales can raise additional issues.
For example, the attorney must consider:
- whether the sale is genuinely needed;
- whether it is in the donor’s best interests if the donor lacks capacity;
- whether there is any conflict of interest;
- whether the attorney or someone connected to them is involved in the transaction; and
- whether further legal authority may be required in unusual circumstances.
An attorney should not treat a property sale as an ordinary personal transaction.
They are acting under a legal duty.
Can an attorney give away my money?
Attorneys have limited powers to make gifts.
They cannot simply give away the donor’s money as though it were their own.
The Mental Capacity Act places restrictions on gifting.
Certain modest gifts may be permitted in limited circumstances, but larger or unusual gifts may require authority from the Court of Protection.
This is an area where attorneys should be particularly cautious.
What duties does an attorney have?
Being appointed as an attorney is a position of responsibility.
Attorneys must follow the principles of the Mental Capacity Act 2005.
Among other things, they must recognise that:
- the donor should be assumed to have capacity unless it is established otherwise;
- the donor should be supported to make their own decisions where possible;
- making an unwise decision does not automatically mean the donor lacks capacity;
- decisions made for someone who lacks capacity must be in their best interests; and
- the least restrictive option should be considered.
Attorneys must also:
- keep the donor’s money separate from their own;
- keep appropriate financial records;
- avoid conflicts of interest;
- act within the authority given by the LPA; and
- use the donor’s money for the donor’s benefit.
The Office of the Public Guardian can investigate concerns about an attorney’s conduct.
How should I choose my attorneys?
Choosing the right attorneys is one of the most important parts of making an LPA.
You should normally choose people who are:
- trustworthy;
- capable of handling financial matters;
- willing to act;
- able to communicate with you and any other attorneys;
- likely to understand and respect your wishes; and
- prepared to keep proper records.
That does not necessarily mean choosing the person who is closest to you emotionally.
Someone may be a loving family member but not necessarily the right person to manage complex finances.
Equally, financial expertise alone is not enough if you do not trust the person.
The right choice depends on your circumstances.
Can I appoint more than one attorney?
Yes.
You can appoint more than one attorney.
You can decide that they should act:
- jointly;
- jointly and severally; or
- jointly for some decisions and jointly and severally for others.
Jointly
The attorneys must make the relevant decisions together.
This can provide an additional safeguard, but it can also make administration less flexible.
If one joint attorney can no longer act, the effect on the remaining appointment needs to be considered carefully.
Jointly and severally
The attorneys can generally act together or independently.
This can make practical administration easier, particularly where attorneys live in different places or cannot always deal with matters at the same time.
Different arrangements for different decisions
It is also possible to require joint decisions for certain matters while allowing attorneys to act independently for others.
The arrangement should be chosen deliberately rather than simply selecting the option that sounds most protective.
Should I appoint replacement attorneys?
Replacement attorneys can provide useful continuity if one of your original attorneys can no longer act.
For example, an attorney may:
- die;
- lose capacity;
- become unwilling to act;
- become bankrupt in circumstances that affect a Property and Financial Affairs appointment; or
- otherwise become unable to continue.
Whether replacement attorneys are appropriate depends on your circumstances and how the original attorneys are appointed.
Can I include instructions or preferences?
Yes.
An LPA can contain appropriate preferences and instructions.
A preference expresses something you would like your attorneys to take into account.
An instruction is binding if it is valid and properly drafted.
These provisions need care.
Poorly drafted wording can create uncertainty, make the LPA difficult to use or in some circumstances cause problems with registration.
It is better to use instructions only where they serve a genuine purpose.
What does it cost to register a Property and Financial Affairs LPA?
As at September 2026, the Office of the Public Guardian registration fee is £92 per LPA.
A person making both:
- a Property and Financial Affairs LPA; and
- a Health and Welfare LPA
would therefore currently pay £184 in government registration fees.
Some donors may qualify for a reduction or exemption depending on their financial circumstances.
Professional fees for advice or preparation are separate from the government registration fee.
Government fees can change, so the current amount should always be checked when an application is made.
How long does registration take?
Current government guidance says that registering an LPA normally takes around 8 to 10 weeks if there are no mistakes in the application.
That means an LPA is best treated as advance planning.
Waiting until somebody urgently needs help can create practical difficulties because the attorney cannot use an unregistered LPA.
Does having an LPA mean my attorney owns my money?
No.
Your attorney does not become the owner of your money, savings, investments or property.
They are managing those assets under legal authority.
The assets remain yours.
An attorney must not treat the donor’s finances as their own.
Do my children automatically have authority if I lose capacity?
No.
Being someone’s child, spouse, civil partner or other close relative does not automatically give legal authority to manage their bank accounts or financial affairs.
A family member normally needs appropriate legal authority before they can act.
That may come from a valid LPA, an Enduring Power of Attorney, a Court of Protection order or another suitable arrangement.
Our guide Why Your Children Can’t Automatically Make Decisions for You explains this common misunderstanding in more detail.
What happens if I lose capacity without a Property and Financial Affairs LPA?
If you lose the relevant capacity and no suitable authority exists, someone may need to consider an application to the Court of Protection.
That could involve deputyship or another form of court order, depending on what needs to be done.
Deputyship can involve:
- a court application;
- evidence of mental capacity;
- court fees;
- ongoing supervision; and
- reporting requirements.
For that reason, an LPA and deputyship are not really alternatives chosen at the same time.
An LPA is something you can choose to put in place while you still have capacity.
Deputyship may become relevant after capacity has already been lost.
See our LPA vs Deputyship guide for a detailed comparison.
Is a Property and Financial Affairs LPA suitable for everyone?
Not necessarily.
Some people have very simple finances and may feel that other arrangements are sufficient for their present needs.
Others may already have existing powers or arrangements that should be reviewed before making a new LPA.
An LPA also requires careful thought about who should be trusted with significant financial authority.
The important thing is to understand what the document does and decide whether it fits your circumstances.
Property and Financial Affairs LPA guidance in Poole, Bournemouth and Christchurch
Brooks Wills supports individuals and families across Poole, Bournemouth, Christchurch and wider Dorset with clear, plain-English guidance on Lasting Powers of Attorney and later-life planning.
If you want to understand how a Property and Financial Affairs LPA could work in your circumstances, you can read more about our Lasting Powers of Attorney services.
You may also find these guides useful:
- Health and Welfare LPA Explained
- Lasting Power of Attorney vs Deputyship
- Why Your Children Can’t Automatically Make Decisions for You
If you are unsure what you need, you can call, message or book a consultation to discuss the next step.
Brooks Wills is a member of the Institute of Professional Willwriters and the Society of Will Writers.
Simplifying legacies, securing tomorrow.
This article provides general information for England and Wales and is not individual legal advice. Mental capacity, attorney authority and the suitability of an LPA depend on the individual circumstances. Government fees and processing times were checked in September 2026 and may change.
Frequently asked questions
Can my attorney use my LPA while I still have capacity?
A registered Property and Financial Affairs LPA can potentially be used while you still have capacity if you have authorised this.
You remain able to make your own decisions.
Can my attorney access my bank account?
Potentially, yes, where the LPA gives the necessary authority.
The bank or building society will normally need evidence of the registered LPA and the attorney’s identity before allowing them to act.
Can my attorney sell my home?
A Property and Financial Affairs attorney may have authority to deal with property, including selling it.
However, the attorney must act within the LPA and comply with their legal duties.
Property transactions involving conflicts of interest or unusual circumstances may require additional consideration.
Can my attorney give money to family members?
Only within limited legal rules.
Attorneys do not have unrestricted power to make gifts from the donor’s money.
Significant or unusual gifts may require Court of Protection authority.
Can I have two attorneys?
Yes.
You can appoint multiple attorneys and specify how they should make decisions.
They may act jointly, jointly and severally, or under a combination of those arrangements depending on the wording of the LPA.
Does my attorney control everything once the LPA is registered?
No.
Registration makes the LPA legally usable, but it does not mean you automatically lose control of your finances.
While you have capacity, your own decisions remain important and must be respected.
What if my attorney can no longer act?
This depends on how your attorneys were appointed and whether replacement attorneys were named.
The effect can vary, which is one reason the attorney structure should be planned carefully when the LPA is created.